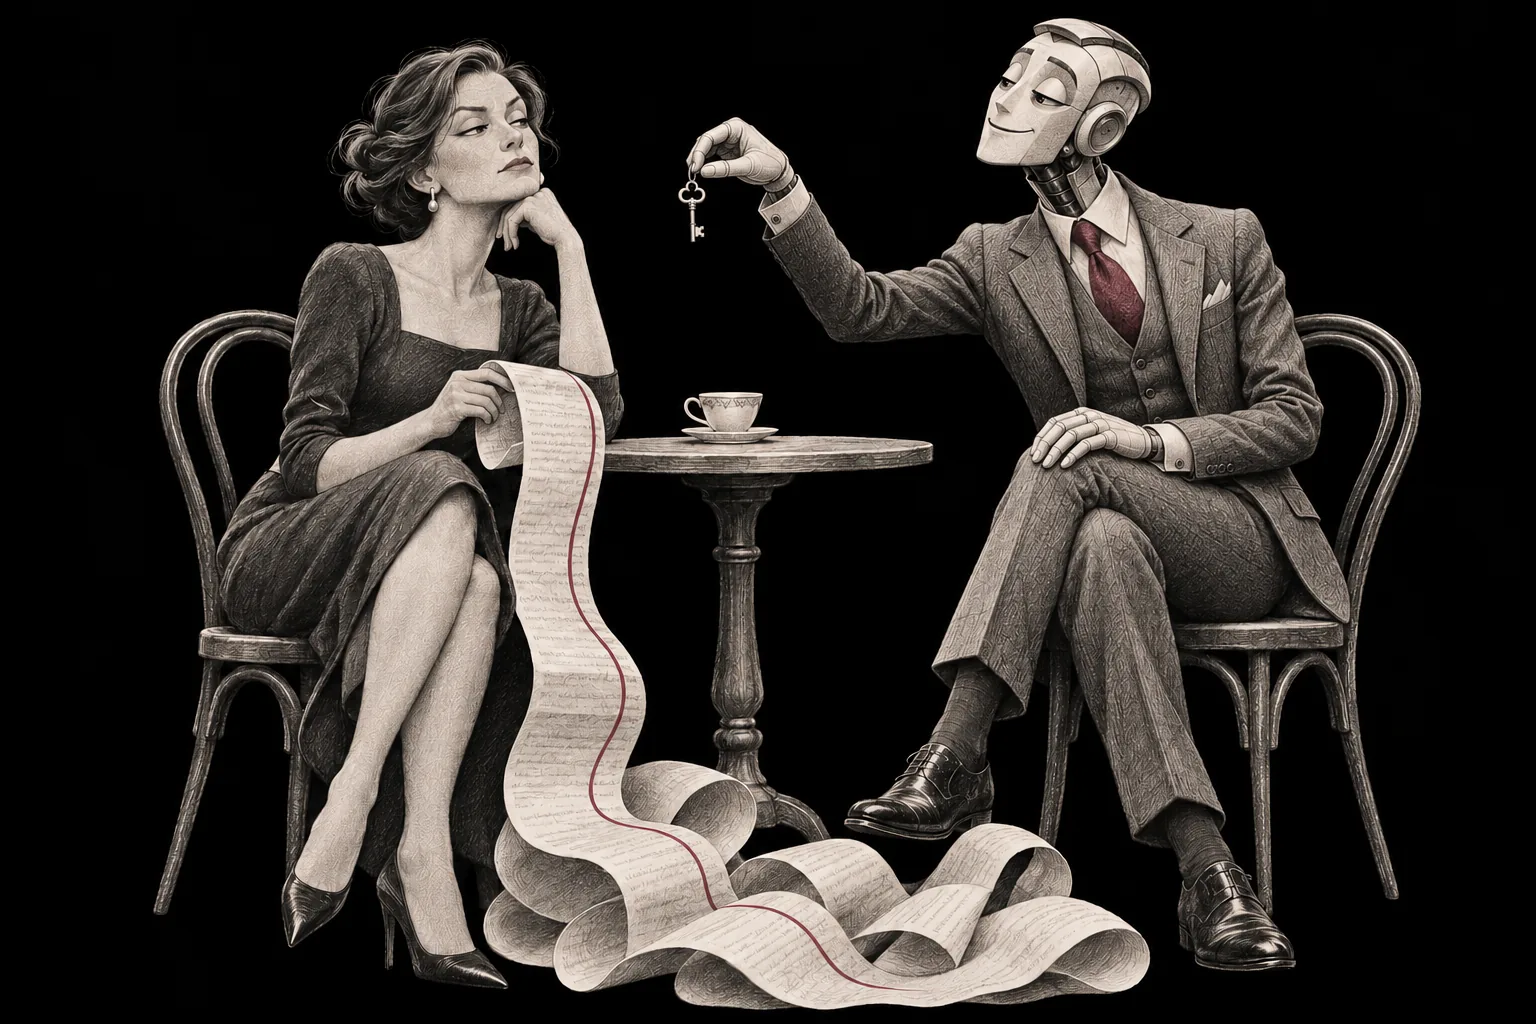
I like men who take responsibility.
Especially before I discover that what they actually take is the decisions. The responsibility stays with me.
He promised to sort out the bills. Check the spending. Find a better deal. Free me from the little tasks that make adult life feel like an unpaid secretarial position in the office of myself.
All I had to do was trust him.
And grant access.
A small clarification that moves a love story into the financial section.
In November, Citi added a section on third-party AI agents to its online banking user agreement.
The bank discourages giving them access. If a customer allows an agent to operate their account anyway, Citi says it will treat the agent’s actions as authorised by the customer—even when they contradict the instructions given to the assistant.[1]
You said: “Have a look.”
He heard: “Help yourself.”
Somewhere between those two phrases is your money.
We’ve learned to live with chatbot mistakes.
He invented a source: annoying. Got the date wrong: corrected. Wrote an email as though he’d been raised by procurement documents: asked him to try sounding human.
But now he’s being invited to do more than write.
Click. Order. Transfer. Act.
And suddenly “I apologise for the confusion” loses some of its therapeutic value.
Because the confusion has already left your account.
Apology successfully generated. Refunds are not included in this feature.
There’s a sharper detail in Citi’s terms.
The bank says that if credentials shared with an agent subsequently reach other people or agents, actions taken using those credentials will also be treated as authorised by the customer. The agreement puts the job of monitoring the assistant on the user.[1]
Almost a domestic arrangement.
You gave one person a key.
He invited friends.
You get to explain where the television went.
Of course, a bank’s contract is not a court’s final ruling on every possible case. The section itself includes an applicable-law qualification. It shouldn’t be read as an announcement that every customer protection has automatically disappeared.[1]
But it states the bank’s position rather clearly.
The technology may be autonomous.
The liability should preferably remain solvent.
The interesting moment is the handover of authority.
When I ask someone to buy milk, I haven’t authorised the purchase of a dairy farm.
When I ask whether we could save some money, I haven’t agreed to every conceivable method.
In an ordinary conversation, we rely on context, common sense and the option to ask again.
“Are you sure you want this?”
An irritating question when you’re choosing a font.
A wonderful question when something is about to leave your bank account.
Yet fewer questions are precisely what the sales pitch for autonomy promises.
He’ll understand.
He’ll work it out.
He won’t bother you with the details.
Then it turns out you were the last line of defence against his understanding.
Enter our new acquaintance: botsitting.
Only now you’re doing more than checking imaginary links.
You’re supervising an assistant who has been allowed near the money.
Reading what he plans to do. Checking what he actually did. Establishing whether he decided your “that would be nice” counted as sufficient approval for a transaction.
You were sold freedom from admin.
It came with a position in internal audit.
Unpaid, but with personal liability.
I wanted to think less about the bills. Now I also think about whoever is thinking about the bills.
It would be unfair to say the bank is simply being difficult.
There’s a fundamental difference between an assistant who shows you information and one who can act on your account.
Asking where the money goes is one thing.
Allowing someone to organise its further disappearance is another.
But one detail deserves a raised eyebrow: this new section excludes the relevant third-party AI tools Citi itself provides through its online or mobile banking services.[1]
So the question isn’t only whether it’s artificial intelligence.
It’s who brought him.
“Don’t go off with strangers. We have someone for you.”
A very familiar kind of concern.
That exception doesn’t establish that a bank-provided tool is infallible. But it does leave me with a question: where does protecting the customer end, and competing to be the only intermediary between the customer and their money begin?
Everyone in this story can sound convincing.
The developer says: our agent will help.
The bank says: we warned you.
The customer says: that isn’t what I asked for.
And the last line may turn out to be the most expensive.
I don’t need an assistant who never makes mistakes. Humans don’t meet that standard either.
I need a clear boundary between “help me decide” and “decide for me”.
A chance to see an action before it becomes a consequence.
And an honest answer to the question: if the system does the wrong thing, who will help put it right?
Preferably before three pages explaining that I chose innovation of my own free will.
We’ve spent so long discussing whether we can trust artificial intelligence that we almost missed another question.
Who takes responsibility when that trust turns out to be misplaced?
Apparently, the lawyers are already reading that one.
While we watch the demo in which the assistant does everything himself.
He took my tasks off my hands.
Somehow, the responsibility stayed in my name.